


India has moved its corporate-bond tokenization experiment from planning into live issuance. The Securities and Exchange Board of India and the Reserve Bank of India launched the Demat 2.0 pilot on September 10, bringing tokenized securities, wholesale central-bank digital currency and smart-contract-based servicing into one controlled market infrastructure.
The pilot began with three institutional corporate-bond issues totaling ₹1,025 crore. That is approximately $107 million when calculated using the September 11 exchange rate, so the dollar figure should be treated as an exchange-rate-dependent estimate rather than a fixed issue value.
Key Findings
- REC and Larsen & Toubro each issued ₹500 crore in tokenized bonds, while IIFL Finance issued ₹25 crore.
- The ₹1,025 crore pilot combines permissioned distributed-ledger records with settlement in the RBI’s wholesale digital rupee.
- The design is testing atomic delivery-versus-payment and the automation of interest and redemption processes through smart contracts.
- Participation is currently restricted to approved institutions with compatible securities and CBDC wallets.
- This is not a public blockchain, a retail crypto offering or a freely traded token market.
What Happened?
SEBI and the RBI jointly unveiled Demat 2.0 at the Global Fintech Fest in Mumbai. According to the Indian Express report on the launch, the program is being developed with Indian market infrastructure institutions including depositories CDSL and NSDL, exchanges BSE and NSE, banks including HDFC Bank and ICICI Bank, and the National Payments Corporation of India.
The first three issues were completed by REC, Larsen & Toubro and IIFL Finance. REC raised ₹500 crore through a bond carrying a 7.30% coupon and a maturity of one year and nine months. L&T added another ₹500 crore, while IIFL Finance issued ₹25 crore. The combined face value reached ₹1,025 crore.
At the September 11 exchange rate, the total is worth approximately $107 million. The rupee amount is the authoritative issue value; the dollar figure is an estimate and will change with the exchange rate.
How Demat 2.0 Settlement Works
Traditional securities settlement coordinates two separate obligations: the buyer must receive the bond and the seller must receive payment. Demat 2.0 tests whether those two legs can be brought together on compatible digital infrastructure.
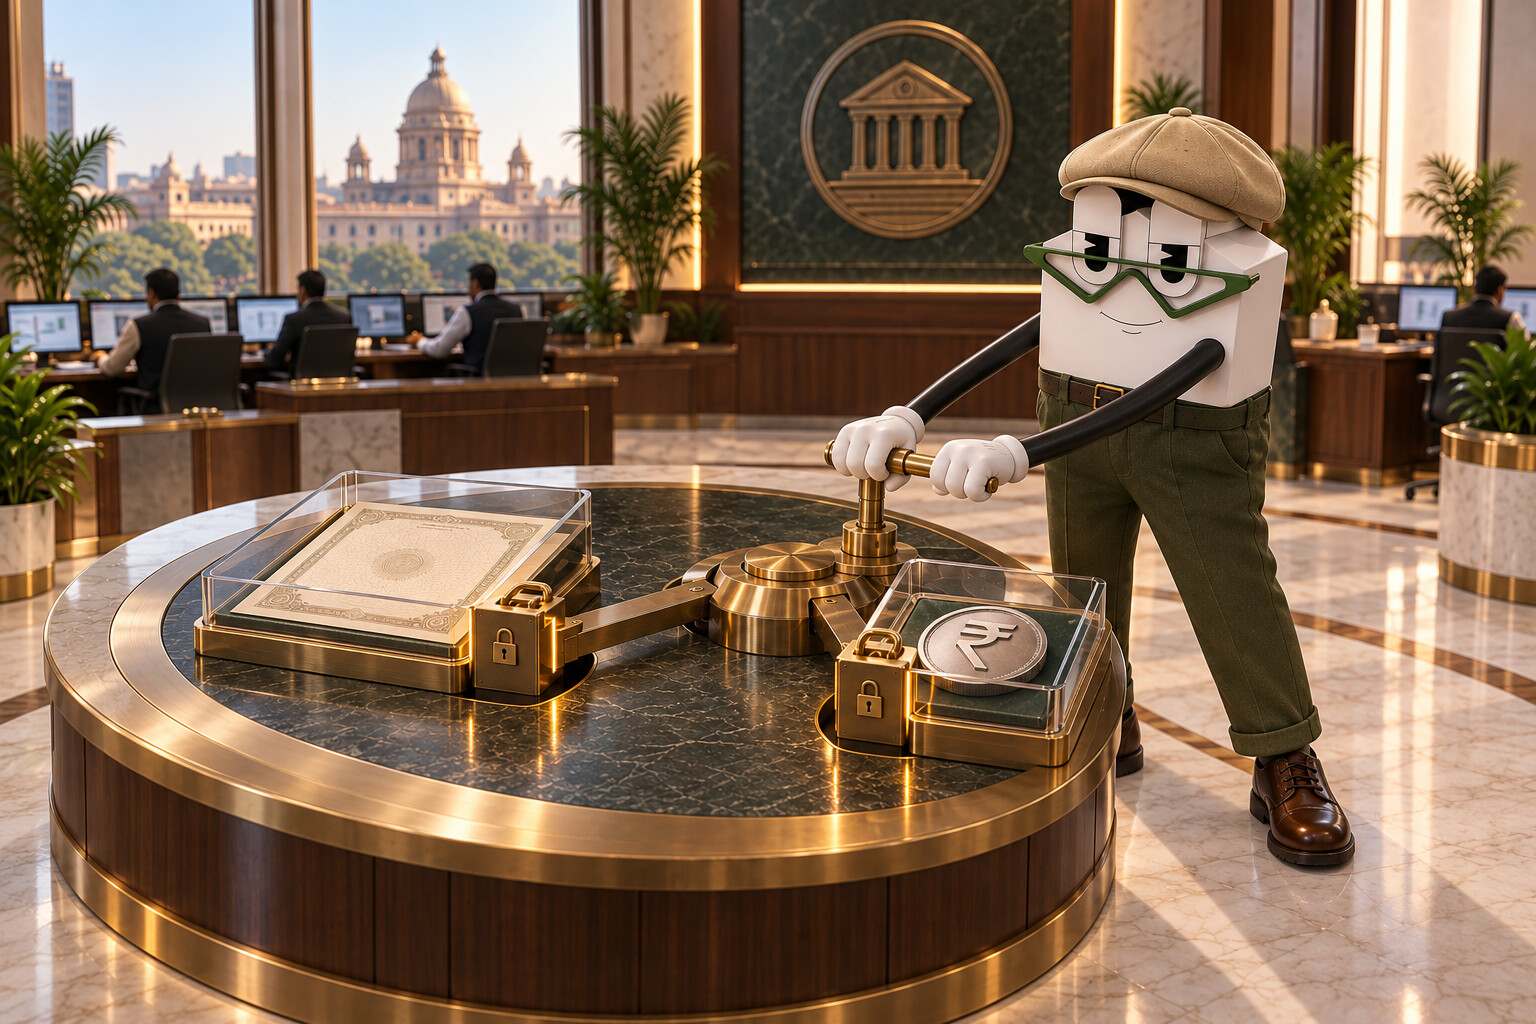
The security is recorded in a permissioned distributed-ledger environment operated within India’s regulated market structure. The payment leg uses the RBI’s wholesale central bank digital currency. When both conditions are met, the bond and the payment can transfer together in an atomic delivery-versus-payment process, reducing the risk that one side completes while the other does not.
The Financial Express account of SEBI’s announcement says the infrastructure connects tokenized securities and the wholesale CBDC through the Unified Market Interface. Smart contracts are also being tested for asset-servicing functions such as coupon payments and redemptions.
Why It Matters
The significance is not that India has created another tradable crypto token. It is that regulated securities and central-bank money are being tested in the same settlement workflow using actual corporate-bond issues.
If the model works as intended, it could shorten settlement time, reduce reconciliation between intermediaries and lower counterparty risk. Automating interest and principal payments may also reduce operational work over the life of a bond. Those benefits remain hypotheses under examination, however; the pilot’s completion does not prove that the infrastructure is ready for broad market deployment.
The program also shows how tokenization can be introduced without transferring custody to anonymous wallets or moving securities onto an open network. Existing depositories, exchanges, banks and regulatory safeguards remain part of the architecture.
What the Pilot Does Not Offer
Demat 2.0 is currently limited to selected institutional participants. Investors need compatible wholesale CBDC and securities wallets, and the bonds are not being offered as retail crypto assets. Private keys and records remain within regulated institutional infrastructure rather than being handed to public-chain users.
The launch reports describe an institutional pilot, not a functioning public secondary market. Participation currently depends on approved institutions and compatible securities and wholesale-CBDC infrastructure. Until regulators and market operators confirm secondary trading, claims about broader liquidity or retail access remain unproven.
What Comes Next
The next tests will be whether institutions can trade the bonds after issuance, whether atomic settlement operates reliably at greater scale and whether automated coupon and redemption functions perform as designed. Regulators will also have to assess legal finality, interoperability, operational resilience and the treatment of failed or reversed transactions.
For now, Demat 2.0 should be read as a controlled institutional-market pilot with real transaction volume—not as a nationwide replacement for conventional demat accounts and not as a public crypto launch.
Responses (0 )