


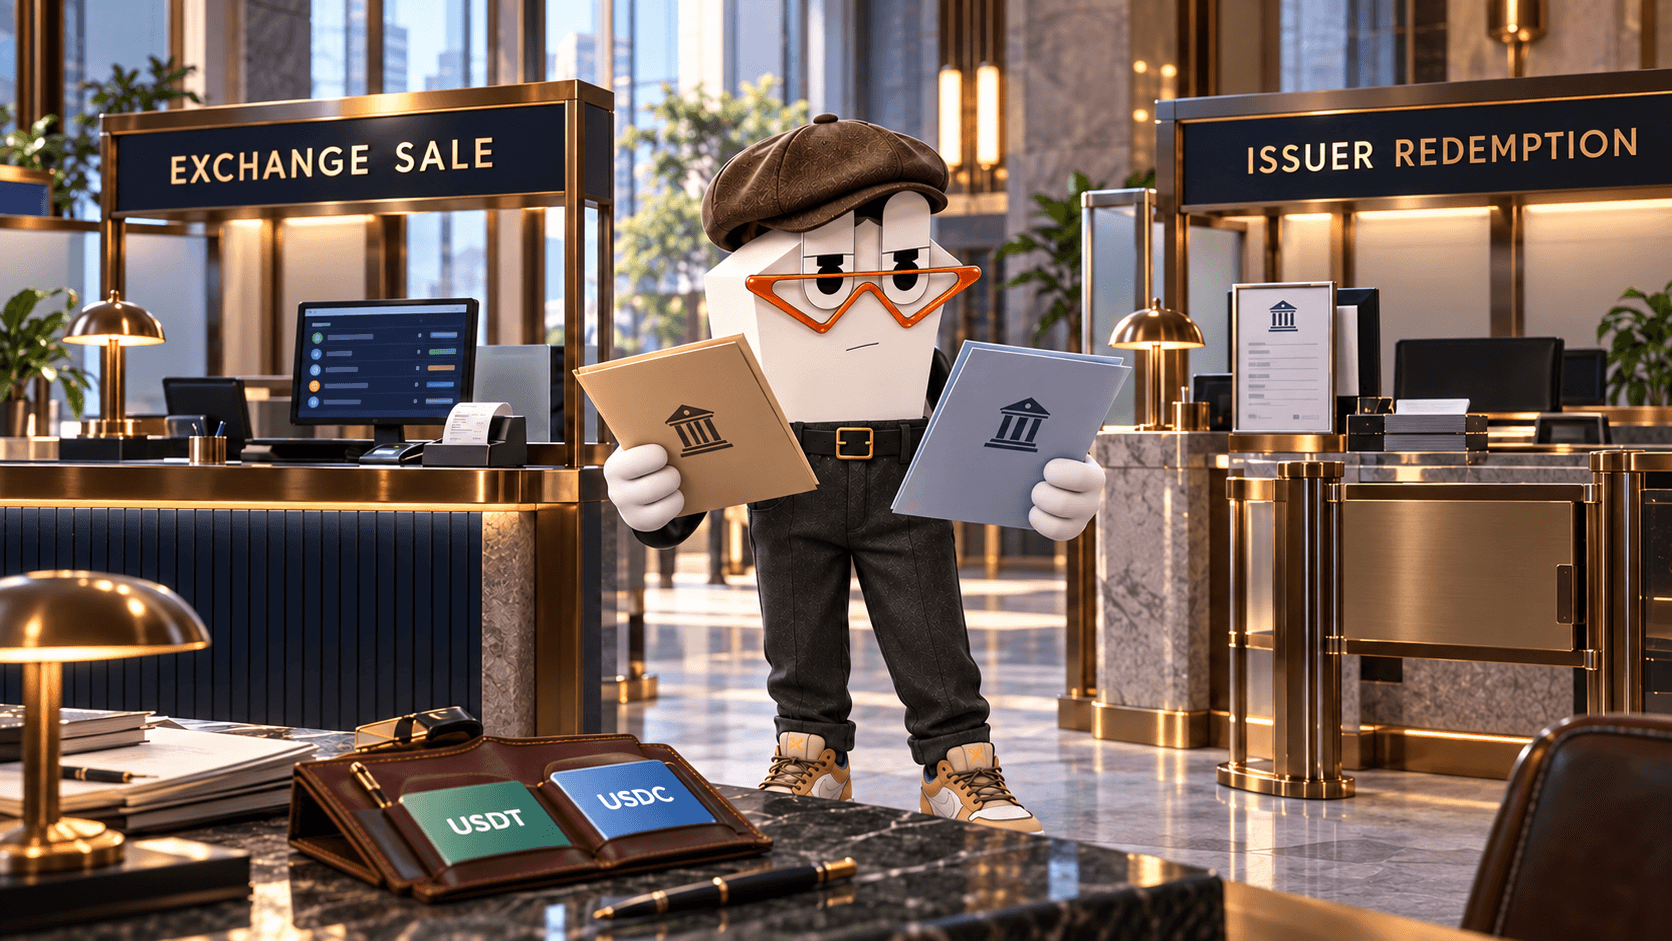
You hold 1,000 USDT or USDC in a wallet. The token is designed to track the U.S. dollar. Does that mean you can send it directly to Tether or Circle and receive $1,000 in your bank account?
Not automatically. Direct stablecoin redemption depends on the issuer, your eligibility, your location, the amount involved, and the applicable service conditions. Selling tokens through an exchange is a different route, even when both processes ultimately produce a dollar balance.
The distinction matters because three statements are often treated as interchangeable: a token targets a $1 market price, an issuer provides redemption at a stated rate, and an individual holder can access that redemption service. They describe different parts of the system.
This guide explains who can redeem USDT and USDC directly, how intermediary cash-outs differ, and why a one-dollar redemption rate does not necessarily mean one dollar arrives in your bank account.
Key Findings
- Selling a stablecoin through an exchange is not the same as redeeming it directly with its issuer.
- Tether’s published direct redemption process requires a verified account and a minimum amount of $100,000 equivalent.
- Circle Mint is an institutional service, not a general-purpose retail account available to individual holders.
- Circle has a separate redemption process for eligible retail holders in the European Economic Area.
- A redemption rate, an exchange execution price, and the net amount credited to a bank account are different figures.
- A token’s name alone does not establish that its network or version is supported by the intended cash-out provider.
Selling, Redeeming, and Withdrawing Are Different Operations
Direct redemption is an issuer-facing process: an eligible customer presents tokens through an approved channel and receives the corresponding fiat value under the applicable terms.
A market sale is different. You exchange the tokens through a trading venue or provider at its available price or conversion rate. Your immediate relationship is with that intermediary, not necessarily with the issuer.
A bank withdrawal is another operation again. A fiat balance shown inside an exchange account must still be transferred through an available payment method before it becomes money credited to your bank account.
For example, Coinbase’s cash-out documentation distinguishes an available cash balance from the crypto that may first need to be sold to create that balance. This illustrates the separation; it is not a recommendation of a particular provider.
| Operation | What happens | What it does not establish |
|---|---|---|
| Direct issuer redemption | An eligible holder uses the issuer’s approved fiat redemption channel. | That every holder can access the same service. |
| Exchange sale or conversion | A provider converts tokens into a cash balance or another asset. | That the holder redeemed directly with the issuer. |
| Bank withdrawal | A provider transfers an available fiat balance through a supported payment method. | That a completed token sale has already reached the bank. |
| On-chain token swap | One blockchain asset is exchanged for another. | That fiat currency has been credited to a bank account. |
A service can combine several steps into one interface. A button labelled “cash out” may hide conversion, custody, compliance checks, and a bank transfer behind a single action. The label does not remove those separate dependencies.
Who Can Redeem USDT Directly with Tether?
Tether’s official redemption guide describes depositing tokens through Tether.to and receiving fiat into a verified bank account. It requires a verified Tether.to account and a minimum redemption amount of $100,000 equivalent.
Verification involves compliance checks. Holding enough tokens does not, by itself, establish that an account will be approved or a particular request accepted.
A holder with 1,000 USDT therefore does not meet the published minimum for this direct channel. That does not establish that the holder cannot sell the tokens through an eligible intermediary; the intermediary has its own requirements.
Tether’s legal terms also contain eligibility restrictions, including restrictions concerning U.S. persons with a specified exception for approved Eligible Contract Participants. They provide for circumstances in which service access or redemptions may be delayed or suspended.
The careful interpretation is that Tether offers a conditional redemption service. It is not an unrestricted bank-withdrawal facility available to anyone who possesses USDT.
How Tether’s Redemption Fee Changes the Calculation
Tether’s published fee schedule lists a redemption fee equal to the greater of $1,000 or 0.1% of the amount redeemed.
The following calculations apply that formula to hypothetical eligible requests. They exclude verification costs, blockchain charges, bank fees, and currency conversion.
| Gross redemption value | Calculated redemption fee | Value after this fee only |
|---|---|---|
| $100,000 | $1,000 | $99,000 |
| $500,000 | $1,000 | $499,000 |
| $1,000,000 | $1,000 | $999,000 |
| $2,000,000 | $2,000 | $1,998,000 |
The $1,000 floor equals 1% of a $100,000 request. At $1 million, it equals 0.1%; above that amount, the percentage component becomes larger.
This is not an exchange-price forecast or a guaranteed bank payout. It demonstrates how the published fee affects the calculation, before other costs.
Who Can Redeem USDC Through Circle Mint?
Circle describes Circle Mint as a service for institutional customers, including exchanges, institutional traders, wallet providers, banks, and consumer-app companies. It explicitly states that Circle Mint is not available to individuals.
For holders outside the European Economic Area, Circle’s USDC terms distinguish customers with a Circle Mint account from holders without one. Direct redemption requires an eligible account in good standing and compliance with the applicable conditions.
Owning USDC therefore does not automatically make someone a Circle Mint customer. The token can be transferred to a new holder without making that holder eligible for every issuer service.
This separates possession of the asset from access to the primary redemption channel. The same distinction helps explain why an intermediary may provide a retail conversion service even when its customer cannot use Circle Mint directly.
The EEA Has a Separate Retail Redemption Process
Circle Mint’s institutional eligibility should not be turned into a worldwide claim that individuals can never redeem USDC directly.
Circle’s MiCA Redemption Policy, updated September 15, 2026, describes a separate process for eligible retail holders established in the European Economic Area.
Retail holders register through a dedicated form, undergo eligibility and identity checks, and provide an EEA bank account. For USDC redemption, that account must accept USD payments. Transaction monitoring and other compliance checks also apply.
The policy warns that third-party bank or currency-conversion charges may occur. Redemption at par therefore should not be confused with an assurance that every receiving bank will credit the full amount without charges.
This is a defined regional process, not a universal retail Circle Mint account. Readers outside the EEA should not assume the same route applies to them.
USDC Redemption Is Not Universally Fee-Free
Circle’s Circle Mint redemption structure describes different pricing tiers and a fee framework updated beginning March 15, 2026.
The schedule distinguishes daily calculations, monthly net redemption adjustments, and possible credits for qualifying activity. Processing characteristics also vary by tier.
A statement such as “Circle always redeems for free” leaves out those conditions. Equally, institutional account pricing should not simply be applied to the separate regional retail process.
The relevant questions are which service is being used, which pricing terms apply, how the customer’s activity is measured, and whether receiving-bank charges are separate.
A Dollar Peg Is Not a Guaranteed Net Bank Receipt
To understand a cash-out quote, separate three figures:
- Reference value: the dollar value the stablecoin is intended to track.
- Conversion value: the amount produced by the specific sale or redemption.
- Net bank receipt: the amount credited after applicable charges and any currency conversion.
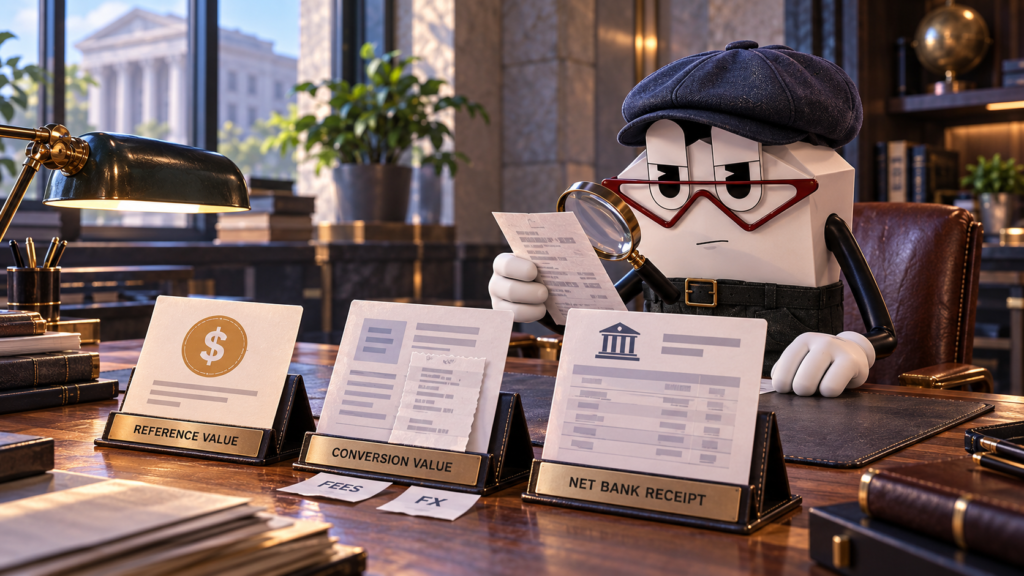
Consider a purely hypothetical intermediary quote of $0.998 per token for 1,000 tokens. The conversion produces $998. If separate conversion and withdrawal charges total $8, the remaining amount is $990, before any additional bank charges.
This example is not a current price, provider quote, or estimate of normal costs. Its purpose is to show why the headline token price alone cannot determine the amount ultimately received.
Currency also matters. Receiving local currency introduces an exchange rate between that currency and the dollar, even if the stablecoin conversion itself occurs at exactly one dollar per token.
The Token and Network Must Match the Redemption Channel
A ticker displayed in a wallet is not sufficient evidence that a deposit will be accepted.
Circle’s supported chains and currencies documentation warns against sending unsupported assets, including bridged USDC, to Circle Mint addresses.
A bridged token and native issuer-supported USDC may have similar names while relying on different systems. The receiving provider must support the actual asset and network involved.
For any route, the provider’s current deposit instructions should determine which asset identifier, blockchain, and destination are valid. The fact that a token can move on-chain does not establish that the intended fiat service will accept it.
What to Check Before Comparing Cash-Out Routes
A useful comparison starts with the route that is actually available to the holder, not the most attractive rate advertised anywhere in the market.
- Eligibility: Does the service accept the customer’s location and account type?
- Asset support: Does it accept this specific token on this network?
- Amount: Are there transaction minimums or account limits?
- Pricing: Is the displayed figure a redemption rate, market price, or conversion quote?
- Costs: Which charges are included, and which may be deducted separately?
- Settlement: Does “completed” mean a token deposit, a cash balance, or money received by the bank?
- Currency: Will the receiving account obtain dollars or a converted local-currency amount?
A hardware wallet does not resolve eligibility, banking access, or provider pricing. Those are separate from control of the signing keys. Our guide to stablecoin freezing and issuer controls explains another important boundary of self-custody.
Likewise, the investment income generated by reserves is separate from the holder’s conversion proceeds. For that distinction, see where stablecoin yield actually comes from.
Frequently Asked Questions
Can I Redeem 1,000 USDT Directly with Tether?
That amount is below Tether’s published $100,000-equivalent minimum. An intermediary sale is a separate route with its own availability and conditions.
Does Owning USDC Give Me a Circle Mint Account?
No. Token ownership does not create an issuer account or satisfy its onboarding requirements. Circle Mint is an institutional service.
Can Individuals Ever Redeem USDC Directly?
Eligible EEA retail holders have a separate process under Circle’s MiCA policy. This should not be generalized to every country.
Is Selling USDC on an Exchange the Same as Redeeming It?
Not in the direct-issuer sense used here. An exchange conversion is a service provided through the intermediary. Its behind-the-scenes settlement arrangements do not make the retail seller a Circle customer.
Does a One-Dollar Rate Guarantee One Dollar in My Bank?
No. The conversion rate and final bank receipt are different measurements. Applicable provider charges, banking costs, and currency conversion must be considered separately.
Does Swapping USDT for USDC Cash Out My Funds?
No. It changes the asset held. A token-to-token swap does not, by itself, create a fiat balance in a bank account.
Bottom Line
The practical question is not simply whether USDT or USDC is “redeemable.” It is whether a particular holder can use a particular redemption channel, under which terms, and with what final result.
Direct issuer redemption, intermediary conversion, and bank withdrawal should be examined separately. A service may connect them, but they remain different operations with different conditions.
Understanding those boundaries makes a one-dollar stablecoin claim more useful: it identifies the reference value without assuming universal access, identical costs, or immediate bank settlement.
Editorial note: Conditions reviewed October 1, 2026. This guide distinguishes direct issuer redemption from intermediary sales and fiat withdrawals. Eligibility, supported networks, fees, and payment arrangements can change. Numerical examples are calculations, not live quotes or guaranteed payouts. The guide does not determine any individual reader’s legal eligibility or recommend a cash-out provider.
Responses (0 )