

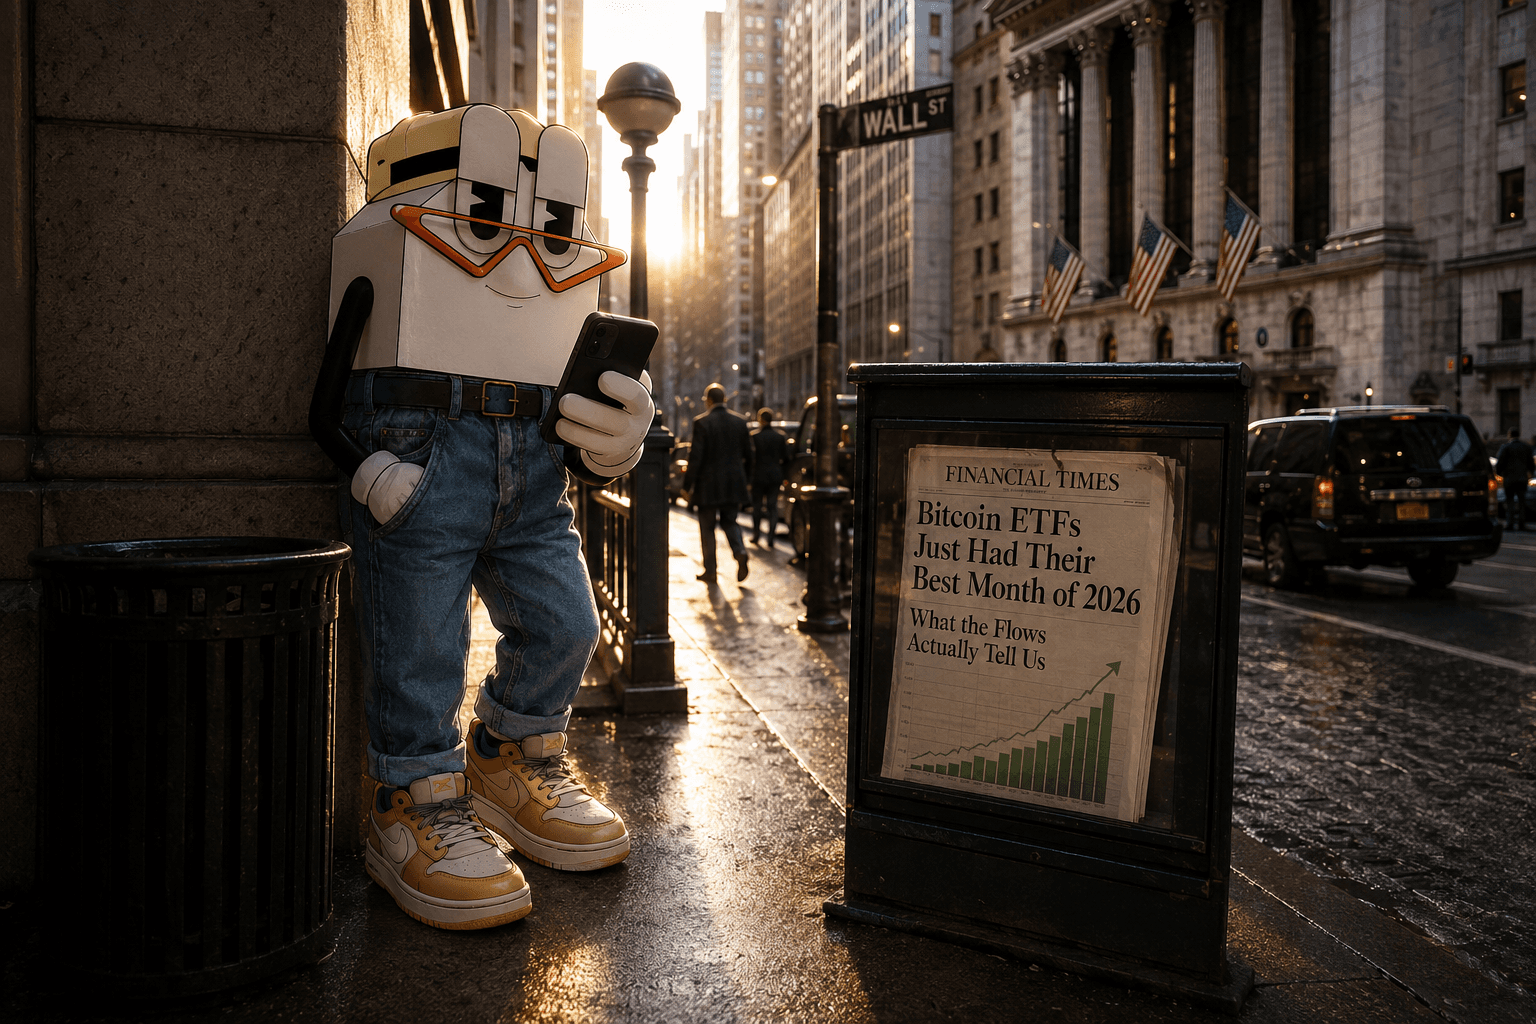

U.S. spot Bitcoin exchange-traded funds entered August with a difficult year behind them. By the end of the month, the picture looked very different.
The funds recorded approximately $3.52 billion in net inflows during August 2026, their strongest monthly performance of the year. Sixteen of the month's 21 trading sessions finished with positive flows, substantially reducing the net outflows accumulated earlier in 2026.
At first glance, the conclusion appears straightforward: investors returned to Bitcoin through ETFs.
But ETF flow data are often asked to tell us more than they actually can.
A billion dollars of net ETF inflows does not automatically mean institutions collectively purchased exactly a billion dollars of Bitcoin from the open market that day. The number does not identify the investors behind those flows. Nor does it prove that ETF demand caused a particular move in Bitcoin's price.
Those distinctions are becoming increasingly important as ETFs develop into a larger part of Bitcoin's market structure.
The more useful question, therefore, is not simply how much capital entered Bitcoin ETFs in August.
It is what those flows actually tell us about the changing structure of the Bitcoin market.
Key Findings
- U.S. spot Bitcoin ETFs recorded approximately $3.52 billion in net inflows during August 2026, their strongest month of the year.
- The recovery was substantial but did not erase the weakness accumulated earlier in 2026, leaving year-to-date flows negative at the end of August.
- ETF flow figures reflect creations and redemptions within investment products and should not automatically be interpreted as an identical amount of immediate open-market Bitcoin buying or selling.
- The SEC's 2025 approval of in-kind creations and redemptions for crypto ETPs made the mechanics behind headline flow numbers even more important to understand.
- Aggregate ETF flows can conceal significant concentration in individual products, particularly dominant funds such as BlackRock's IBIT.
- ETF flow data alone do not reveal whether the underlying investors are institutions, advisers, hedge funds, trading firms or individual investors.
- Bitcoin ETFs increasingly function as part of Bitcoin's broader liquidity and market infrastructure rather than merely as a proxy for “institutional interest.”
August Changed the ETF Picture
The scale of August's reversal deserves attention.
U.S. spot Bitcoin ETFs entered the month after a difficult period for flows. By the end of July, cumulative net outflows for 2026 had reached approximately $5.29 billion.
August reduced that deficit substantially.
Approximately $3.52 billion flowed into the products during the month, leaving year-to-date net outflows at roughly $1.77 billion. Total net assets across the group reached approximately $99.61 billion, while monthly trading volume was approximately $58.63 billion.
Bitcoin was strengthening at the same time.
That combination naturally produced a familiar interpretation: ETF demand was returning as Bitcoin's market strengthened.
There is useful information in that conclusion.
But there is also an important analytical distinction.
ETF flows and Bitcoin buying pressure are related concepts. They are not identical concepts.
Understanding why requires looking inside the machinery of an ETF.
What Does a Bitcoin ETF Inflow Actually Mean?
When investors buy shares of a Bitcoin ETF on an exchange, those shares can simply change hands between market participants.
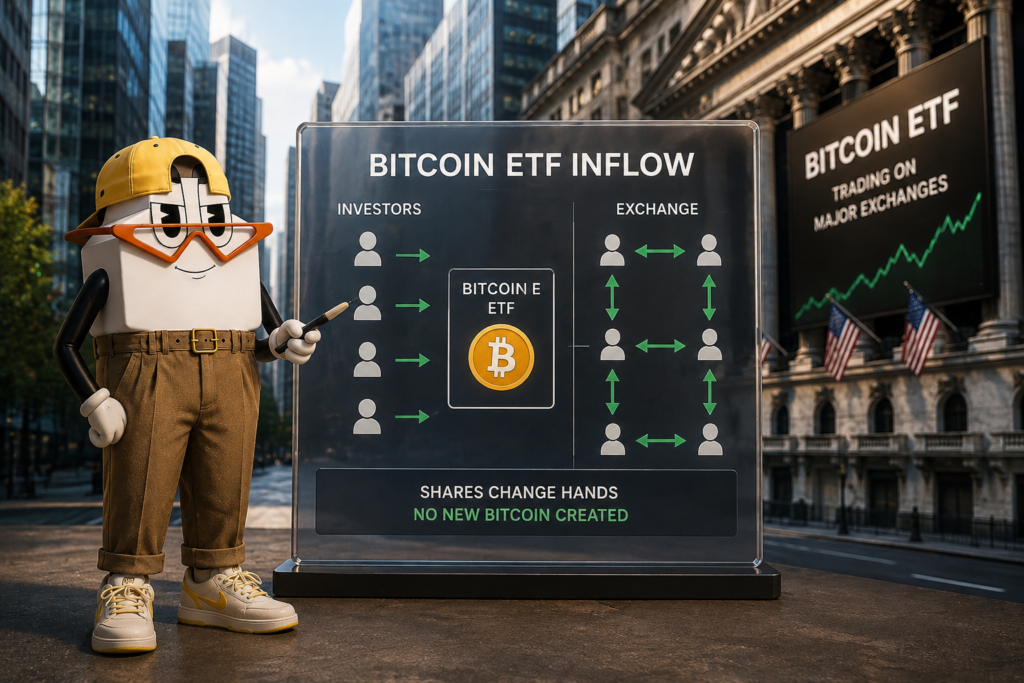
That secondary-market transaction does not by itself mean the fund must acquire additional Bitcoin.
The more important mechanism appears when demand and supply conditions lead specialized financial institutions known as authorized participants to create or redeem ETF shares.
Creation adds new ETF shares.
Redemption removes them.
These processes help keep the ETF's market price aligned with the value of the assets underlying the product.
This distinction matters because the daily “net flow” figures followed across crypto markets primarily describe net capital associated with fund creations and redemptions. They are not a transaction-by-transaction ledger showing every investor buying Bitcoin in the spot market.
And since 2025, the mechanics behind those flows have become even more important.
The SEC Changed How Crypto ETFs Can Create and Redeem Shares
When U.S. spot Bitcoin ETFs were initially approved, their creation and redemption processes operated under a cash-based model.
That changed on July 29, 2025.
The U.S. Securities and Exchange Commission approved orders permitting in-kind creations and redemptions for crypto asset exchange-traded products, bringing their structure closer to the mechanisms available to other commodity-based ETPs.
Under an in-kind structure, Bitcoin itself can be delivered or received through the creation and redemption process rather than requiring every transaction to move entirely through cash.
This is not merely a technical detail.
It changes how headline ETF-flow numbers should be interpreted.
Consider a common statement:
“Bitcoin ETFs received $500 million today, so Wall Street bought $500 million of Bitcoin.”
The economic effect of ETF demand can ultimately translate into demand for Bitcoin. But the statement above is not a precise description of how the ETF machinery necessarily operates.
Depending on whether creations are conducted through cash or Bitcoin, the inventory available to authorized participants and activity elsewhere in the market, the relationship between a reported ETF inflow and immediate open-market Bitcoin purchases can be more complicated.
The flow number therefore tells us something important about capital moving through the investment product.
It does not provide a perfect real-time measurement of spot-market Bitcoin buying.
ETF Flows Do Not Tell Us Who Is Buying
There is another problem with describing every positive ETF flow as “institutional buying.”
Daily ETF flow tables do not identify the ultimate investor behind every dollar.
A Bitcoin ETF can be purchased through a registered investment adviser, hedge fund, proprietary trading operation, institutional portfolio or an individual brokerage account.
Those investors may also be pursuing completely different strategies.
One investor may be establishing long-term Bitcoin exposure.
Another may be hedging exposure elsewhere.
Another could be participating in an arbitrage strategy.
Another may simply be trading short-term market momentum.
The resulting activity can eventually contribute to the same aggregate ETF flow figure.
That means a useful analytical distinction is necessary:
ETF inflow does not automatically equal institutional conviction.
Flows provide evidence of demand moving through the investment vehicle. Determining who is responsible for that demand — and why — requires additional information.
Aggregate Numbers Can Hide Concentration
Daily totals create another potential analytical trap.
Imagine the Bitcoin ETF market records $250 million in net inflows.
The headline sounds like broad demand.
But suppose one fund receives $300 million while several competing products collectively experience $50 million of net outflows.
The aggregate result remains positive.
The underlying picture is very different.
That type of concentration has already appeared in the U.S. Bitcoin ETF market.
On August 27, BlackRock's IBIT recorded approximately $277.6 million in net inflows, while the entire U.S. spot Bitcoin ETF group recorded roughly $242 million in net inflows. Outflows from other products partially offset IBIT's result.
In effect, a single product generated more than 100% of the market's net positive result for that session.
This is why flow breadth matters.
A market in which most major funds are simultaneously attracting capital conveys a different signal from a market whose positive headline figure is overwhelmingly produced by one dominant product.
IBIT Has Become Part of the Market Structure Story
The concentration around BlackRock's IBIT highlights a broader development.
Bitcoin ETFs are not merely creating another route into Bitcoin.
They are creating financial intermediaries of very different sizes within that route.
IBIT has developed into the dominant U.S. spot Bitcoin ETF, giving one of the world's largest asset managers a major position within Bitcoin's regulated investment infrastructure.
That does not mean BlackRock controls Bitcoin.
The Bitcoin network remains independent of any ETF issuer.
But ownership of Bitcoin and control over important access channels to Bitcoin exposure are different questions.
As ETF assets grow, issuers, custodians, authorized participants, market makers and securities exchanges form an increasingly important layer connecting parts of traditional finance with the underlying Bitcoin market.
That layer deserves analysis in its own right.
Why ETF Inflows and Bitcoin Price Often Move Together
None of this means ETF flows are irrelevant to Bitcoin's price.
Sustained net creations can contribute to demand for Bitcoin held by ETF structures. Regulated investment products can also broaden the pool of capital capable of gaining Bitcoin exposure.
The important distinction concerns causality.
Bitcoin can strengthen while ETF inflows increase because both are responding to the same broader market conditions.
Higher Bitcoin prices can themselves attract additional investors.
ETF demand can contribute to buying pressure.
Derivatives positioning can influence spot markets.
Liquidity conditions can change simultaneously.
Corporate Bitcoin purchases and other large holders can introduce additional sources of demand.
Several of these mechanisms can operate at the same time.
Consequently, observing:
ETF inflows rise while Bitcoin's price rises
does not automatically prove:
ETF inflows caused the entire Bitcoin move.
Markets rarely provide causality that cleanly.
ETFs Are Changing Bitcoin's Market Structure
This is where the August numbers become more interesting than the headline.
For much of Bitcoin's history, gaining exposure generally meant interacting directly with cryptocurrency exchanges, custody providers or Bitcoin itself.
Spot ETFs changed that relationship.
An investor can now gain Bitcoin price exposure through much of the same brokerage and portfolio infrastructure used for equities, bonds and conventional ETFs.
That seemingly simple change has substantial consequences.
Bitcoin exposure can increasingly sit inside portfolio-management systems, advisory platforms and institutional workflows that were not originally designed around crypto-native infrastructure.
The underlying asset has not changed.
The rails through which portions of traditional capital reach it have.
And those rails now include some of the largest firms in global asset management.
ETF Infrastructure Works in Both Directions
August also provides a useful reminder about financial infrastructure.
It works in both directions.
The same ETF structure that makes Bitcoin exposure easier to obtain through traditional financial accounts also makes that exposure relatively straightforward to reduce.
Strong inflows therefore should not be viewed exclusively as a permanent accumulation mechanism.
ETFs are better understood as a capital transmission channel.
Capital can enter.
Capital can leave.
And as the ETF ecosystem becomes larger relative to Bitcoin's overall market, activity in both directions becomes increasingly relevant to market analysis.
What ETF Flows Can — and Cannot — Tell Us
ETF flows remain valuable data.
They can show whether investment products are experiencing net creations or redemptions.
They can reveal which issuers are gaining or losing assets.
They can help identify sustained demand trends.
And they can show whether capital movement is broadly distributed or concentrated in particular products.
But the data become misleading when asked to answer questions they cannot answer.
ETF flows alone cannot tell us precisely who bought.
They cannot reveal why the investor bought.
They cannot establish whether that position is hedged elsewhere.
And they cannot prove that a particular Bitcoin price movement was caused by ETF activity.
With crypto ETPs now able to use in-kind creations and redemptions, the headline dollar figure also should not automatically be treated as an identical amount of immediate spot-market Bitcoin buying or selling.
The distinction may sound technical.
For a Bitcoin market increasingly connected to traditional financial infrastructure, it is becoming fundamental.
What Happens Next?
One month of strong inflows does not establish a permanent trend.
Instead of extrapolating August indefinitely, several indicators deserve attention over the coming months.
The durability of net flows matters.
So does the distribution of those flows across issuers.
The growth or contraction of ETF assets relative to Bitcoin's broader market matters.
And the relationship between ETF activity, spot-market liquidity and derivatives positioning deserves increasingly careful analysis.
The question is therefore becoming more sophisticated than:
“Are institutions buying Bitcoin?”
A better question is:
“How is traditional financial infrastructure changing the way capital enters and exits the Bitcoin market?”
The Bigger Picture
The launch of U.S. spot Bitcoin ETFs was initially treated primarily as an access story.
That phase is increasingly behind us.
Access exists.
The next phase is about market structure.
Bitcoin now trades simultaneously across crypto-native exchanges, derivatives markets, institutional custody systems and regulated investment products connected to traditional brokerage infrastructure.
ETFs sit at the intersection of several of those systems.
August's approximately $3.52 billion in net inflows demonstrates how significant that channel has become.
But the number should not be mistaken for something it is not.
It is not a direct measure of institutional conviction.
It is not a perfect proxy for Bitcoin spot demand.
And it is not proof of why Bitcoin's price moved.
It is evidence of capital moving through an increasingly important financial rail.
That may ultimately be the more consequential development.
The important story is no longer whether Wall Street has access to Bitcoin. It is how that access is changing the structure through which Bitcoin is bought, held, traded and redeemed.
Primary Sources & Data
- U.S. Securities and Exchange Commission: Regulatory material covering the July 2025 approval of in-kind creations and redemptions for crypto asset ETPs.
- ETF Flow Data: Fund-level and aggregate U.S. spot Bitcoin ETF flow data used to evaluate August 2026 creations, redemptions and market concentration.
- BlackRock / iShares: Official product information used to examine the structure and development of the iShares Bitcoin Trust ETF.
Sources & Methodology
The Crypto Public reviewed regulatory documents, official fund information, ETF-level flow data and contemporary market reporting. ETF flows are treated as evidence of creations and redemptions within investment products rather than as direct measurements of investor identity, motivation or market causality. Figures may vary slightly between data providers because of reporting methodologies and subsequent revisions.
Responses (0 )