


Twenty-one major financial institutions are preparing to launch a shared U.S. dollar stablecoin in 2027, bringing some of the world’s largest banks and asset managers into a market still dominated by crypto-native issuers.
The headline is significant. But the more important development is structural.
Banks are no longer simply experimenting with blockchain technology or debating whether stablecoins belong inside regulated finance. Some of the world’s largest financial institutions are now attempting to build the infrastructure themselves.
The project brings together Bank of America, Citi, Goldman Sachs, Deutsche Bank, UBS, Wells Fargo, Fidelity Investments and other institutions across North America, Europe, Asia, the Middle East and Africa.
Their first planned product is a U.S. dollar-denominated stablecoin backed 1:1 by reserves and designed to operate across public blockchains. Other G7 currencies could follow, with the euro identified as an early priority.
The stablecoin is expected to launch in the first half of 2027, subject to regulatory and other conditions.
That makes this more than another institutional blockchain pilot.
It raises a larger question for digital finance:
If stablecoins become a permanent layer of the financial system, who will control the money moving across that layer?
For years, the answer has largely been crypto-native issuers.
Banks increasingly appear unwilling to assume that will remain the case.
Key Findings
- Twenty-one financial institutions plan to establish a joint stablecoin enterprise, with a U.S. dollar-denominated token targeted for the first half of 2027.
- The proposed stablecoin is expected to be backed 1:1 by reserves and designed for use across public blockchains rather than being restricted to a closed banking network.
- The consortium includes major banks and investment firms across several regions, making it broader than a single-bank tokenization project.
- Cross-border payments and digital-asset settlement are among the planned use cases, while additional G7 currency stablecoins may follow.
- The project arrives as regulated stablecoin frameworks become clearer, particularly in the United States and Europe.
- Bank sponsorship does not guarantee adoption. Existing stablecoins already benefit from substantial liquidity, exchange integration and network effects that new institutional tokens will have to overcome.
- The emerging competition may ultimately be less about individual tokens and more about which financial networks become the settlement layer for tokenized money and assets.
What Are the 21 Institutions Actually Building?
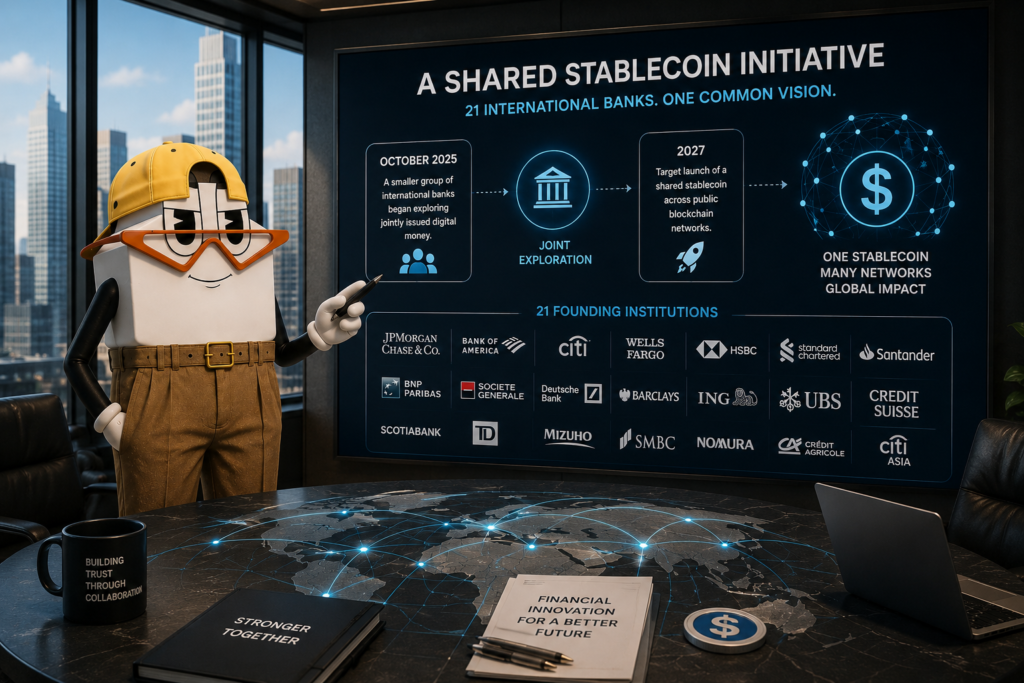
The project began in October 2025 with a smaller group of international banks exploring whether jointly issued digital money could provide benefits across public blockchain networks.
It has since expanded substantially.
According to the consortium’s September 2026 announcement, the group now includes 21 financial institutions:
North America: Bank of America, Capital One, Citi, Fidelity Investments, Goldman Sachs, PNC Financial Services, Scotiabank, TD Bank Group, Wells Fargo and WisdomTree.
Europe: Santander, BBVA, Commerzbank, Crédit Agricole, Deutsche Bank, Lloyds Banking Group, Rabobank and UBS.
East Asia: MUFG Bank.
Middle East: Sirius International Holding.
Africa: Standard Bank.
The group intends to establish a new company in the second half of 2026 and launch its first stablecoin during the first half of 2027, provided regulatory and other requirements are satisfied.
The initial token would be denominated in U.S. dollars.
The consortium says the stablecoin would be backed 1:1 by reserves and capable of operating across public blockchains.
That final detail matters.
Financial institutions have spent years developing permissioned blockchain systems where participation is tightly controlled. A token designed to circulate across public networks points toward a different model: regulated money interacting with blockchain infrastructure that already supports global digital-asset markets.
The consortium has not yet disclosed which blockchains will be supported.
It has also not announced a token name, detailed reserve composition, redemption structure or final governance model.
Those unknowns are important. The project is substantial, but it remains a planned financial infrastructure product rather than a functioning stablecoin network.
Why Would 21 Institutions Issue One Token Together?
A stablecoin becomes useful when other people are willing to accept it.
That sounds obvious, but it creates one of the largest barriers facing any new issuer.
Money is fundamentally a network product.
A technically sound token with strong reserves can still struggle if exchanges do not list it, wallets do not support it, merchants do not accept it and financial institutions cannot easily settle with it.
This creates a strategic problem for banks.
A Citi stablecoin might be trusted by Citi clients. A Deutsche Bank token might work well inside Deutsche Bank's ecosystem. A Goldman Sachs token could have institutional applications.
But fragmented bank-issued tokens could recreate one of the problems blockchain-based settlement is supposed to reduce: separate pools of money that need bridges between them.
A jointly issued stablecoin could approach the problem differently.
Instead of asking users and institutions to adopt dozens of bank-specific tokens, multiple financial institutions could support a common settlement asset.
That potentially concentrates liquidity, reduces fragmentation and gives the token a larger distribution network from launch.
The consortium structure therefore may be as important as the stablecoin itself.
These institutions are not merely pooling technology.
They may be attempting to pool network effects.
Stablecoins and Bank Deposits Are Not the Same Thing
The entrance of banks into stablecoins can make an important distinction easy to miss.
A stablecoin is not simply a bank deposit placed on a blockchain.
Traditional commercial-bank deposits represent liabilities of individual banks. Customers hold claims against those institutions, and those deposits operate inside a regulated banking system with specific legal, capital and deposit-protection structures.
Tokenized deposits can digitize those same bank liabilities.
Stablecoins are structured differently.
A payment stablecoin typically represents a token issued against a pool of reserve assets designed to maintain redemption at a fixed value, such as one U.S. dollar.
That difference affects who issues the money, what supports it, how redemption works and where it can circulate.
The distinction becomes particularly important as banks explore both models.
Financial institutions do not necessarily have to choose between tokenized deposits and stablecoins.
They could use tokenized deposits for some banking relationships while stablecoins serve as more portable settlement instruments across blockchain networks.
The future of on-chain money may therefore contain multiple forms of regulated digital cash rather than one universal model.
Why Public Blockchains Matter
One of the most consequential elements of the consortium’s proposal is its intention to make the stablecoin available across public blockchains.
Public networks already contain much of the infrastructure that makes stablecoins useful.
Exchanges, wallets, decentralized applications, custody platforms and tokenized assets can interact through shared blockchain standards.
A stablecoin confined to a private institutional ledger might improve certain back-office processes but would have limited access to this wider ecosystem.
Public-chain compatibility potentially changes that.
It could allow regulated financial institutions to issue money that interacts with digital markets without requiring those markets to migrate onto proprietary banking infrastructure.
But public blockchains also create complications.
Banks operate under strict requirements involving customer identification, sanctions screening, transaction monitoring and financial-crime controls.
Public networks are open by design.
Reconciling those two systems will likely require controls at the issuer, wallet, custody and redemption layers.
The important question therefore is not simply whether banks will use public blockchains.
It is how much openness regulated bank-backed money can actually retain once compliance requirements are applied.
Why Stablecoins Have Become Strategically Important to Banks
Stablecoins began largely as infrastructure for cryptocurrency markets.
They allowed traders to move dollar-like value between exchanges and blockchain networks without repeatedly returning to traditional bank rails.
Their role has since expanded.
Stablecoins are increasingly used for payments, settlement, remittances, treasury operations and movement between tokenized financial assets.
That expansion matters to banks because payments and settlement are not peripheral banking functions.
They are core financial infrastructure.
If a meaningful portion of money movement shifts onto blockchain networks, banks face a strategic choice.
They can provide the money used on those networks, provide the infrastructure around it, or allow other issuers to become increasingly important intermediaries.
The 21-institution project suggests that at least some major financial firms are choosing the first two options.
The Regulatory Timing Is Not Accidental
The project is emerging as stablecoin regulation becomes clearer in major financial jurisdictions.
In the United States, the GENIUS Act established a federal framework for payment stablecoins after becoming law in July 2025.
The framework created rules around permitted issuers, reserve requirements, disclosures and supervision.
For financial institutions, regulatory clarity changes the calculation.
Stablecoins become easier to treat as a potential financial product when institutions know which entities can issue them, what reserves must support them and which regulators will oversee them.
Europe has followed a different regulatory path through the Markets in Crypto-Assets framework, commonly known as MiCA.
The specific rules differ, but the direction is similar.
Stablecoins are moving from a regulatory grey area toward formal financial frameworks.
That does not eliminate regulatory risk.
It does make large-scale institutional projects easier to plan.
The Banks Are Not Entering an Empty Market
The biggest challenge facing the consortium may not be technology or even regulation.
It may be distribution.
Stablecoins already have incumbents.
Tether's USDT has grown to more than $180 billion in circulation, according to Reuters, while Circle's USDC has established substantial liquidity across exchanges, wallets and blockchain networks.
Their advantage is not merely size.
It is integration.
A stablecoin becomes more useful as more exchanges quote trading pairs against it, more wallets support it, more blockchain applications accept it and more counterparties are willing to receive it.
Those integrations accumulate over time.
This creates a powerful network effect.
A bank-backed token may enter the market with strong institutional credibility, extensive customer relationships and access to established payment infrastructure.
But it will still need users.
And users already have alternatives.
Institutional Credibility Does Not Guarantee Adoption
Traditional finance has already produced examples showing that institutional sponsorship alone does not create stablecoin scale.
Société Générale's digital-asset subsidiary has issued regulated stablecoins, including a dollar-denominated token.
Yet Reuters reported circulation of its dollar stablecoin at only around $12.5 million as the new 21-institution project was announced.
That does not make the project unsuccessful.
It illustrates something more important.
Stablecoin adoption depends on more than regulatory credentials.
Liquidity matters.
Exchange support matters.
Wallet compatibility matters.
Redemption matters.
Developer integration matters.
And perhaps most importantly, users need a reason to move from money that already works.
The new consortium begins with considerably greater distribution potential than a single issuer.
But even 21 major financial institutions cannot manufacture network effects instantly.
A Parallel Stablecoin Race Is Already Developing in Europe
The new global consortium is not operating in isolation.
European financial institutions are developing another major bank-backed stablecoin initiative through Qivalis.
The consortium has expanded to dozens of participating financial institutions across Europe and is working toward a regulated euro-denominated stablecoin.
The parallel development is revealing.
Large financial institutions are beginning to approach stablecoins as shared infrastructure rather than isolated experiments.
One group is initially targeting the U.S. dollar.
Another is building around the euro.
Individual banks and fintech companies are developing additional tokens.
Crypto-native issuers already operate global stablecoin networks.
The result could be a much more fragmented — and competitive — stablecoin landscape.
Why the Euro Could Be the Next Step
Although the 21-institution consortium plans to begin with a U.S. dollar stablecoin, it has already identified other G7 currencies as potential future products.
The euro is an early priority.
That matters because stablecoins remain heavily dollarized.
Dollar-denominated tokens dominate existing crypto settlement infrastructure, reinforcing the dollar's role inside digital-asset markets even when transactions occur outside the United States.
A credible euro stablecoin backed by major financial institutions could offer an alternative for European businesses, financial institutions and tokenized markets that do not want every blockchain transaction to rely on dollar-denominated settlement.
But the consortium could eventually face direct competition from Qivalis and other euro-focused projects.
The stablecoin market may therefore develop along currency lines as well as issuer lines.
Cross-Border Payments Are One of the Biggest Opportunities
The consortium has identified cross-border payments as one potential use case.
That is not surprising.
International money movement can involve correspondent banks, different operating hours, multiple ledgers and several intermediaries before settlement is complete.
Blockchain networks can operate continuously and transfer tokenized value directly between participants.
A widely accepted stablecoin could therefore reduce some settlement friction.
But claims that stablecoins simply “replace SWIFT” are usually too simplistic.
Correspondent banking relationships, liquidity, compliance, foreign-exchange conversion and final settlement involve additional systems and institutions.
Stablecoins could change parts of that architecture without eliminating every layer.
The more realistic question is which settlement functions can move onto blockchain networks — and which intermediaries remain necessary when they do.
The Reserve Model Creates Another Strategic Question
Stablecoins do not only create payment infrastructure.
They create reserve pools.
A 1:1-backed stablecoin requires assets capable of supporting redemptions.
Depending on the regulatory structure and reserve composition, those assets may include cash, central-bank deposits, short-term government securities or other highly liquid instruments.
At sufficient scale, those reserves become economically significant.
Crypto-native stablecoin issuers have already demonstrated how large these balance sheets can become.
For banks, however, the economics are more complicated.
Traditional banks already generate revenue by intermediating deposits and extending credit.
A fully reserved stablecoin can behave differently from a conventional bank deposit.
That means banks entering stablecoins are not simply copying the existing banking model onto blockchain rails.
They may be creating a new category of balance-sheet and settlement infrastructure alongside it.
How reserve income, operating costs and economic benefits are distributed across 21 participating institutions will therefore be an important detail when the consortium reveals its final structure.
What Could Stop the Project From Succeeding?
The list of participating institutions is impressive.
The list of unresolved questions is equally important.
The consortium still needs to establish its operating company and satisfy regulatory requirements.
It has not disclosed the final token structure.
It has not identified supported blockchains.
It has not explained the complete redemption mechanism.
It has not published the reserve portfolio.
It has not revealed how governance will work between participating institutions.
And it has not demonstrated user demand.
There are also strategic coordination risks.
A consortium of 21 institutions can provide enormous distribution.
It can also make decision-making more complicated.
Participants operate in different jurisdictions, serve different customers and may have different commercial priorities.
A shared stablecoin only works as shared infrastructure if the members continue to agree on how that infrastructure should evolve.
The Real Competition May Be Between Networks, Not Tokens
Stablecoin discussions often focus on market capitalization.
Which token is largest?
Which issuer has the most reserves?
Which stablecoin processes the most volume?
Those metrics matter.
But the next phase of competition may increasingly happen one level higher.
USDT is not useful simply because Tether issues tokens.
It is useful because an enormous network of exchanges, wallets, traders, payment providers and blockchain applications recognizes those tokens.
The same applies to USDC.
The 21-institution consortium is attempting to build a different kind of network advantage.
Its members already connect to millions of customers, corporations, investment portfolios and payment relationships across the traditional financial system.
If those relationships can be connected to a common blockchain settlement asset, the consortium could bring an existing financial network on-chain rather than building one entirely from scratch.
That is potentially powerful.
But the two networks are not the same.
Crypto-native stablecoins have deep blockchain liquidity.
Banks have deep relationships with the traditional economy.
The important question is what happens as those networks begin to overlap.
What Happens Next?
Several developments will determine whether the project becomes a major stablecoin network or remains primarily an institutional infrastructure experiment.
The establishment of the new operating company will be the first milestone.
Regulatory approvals will follow.
Then the consortium will need to reveal details that matter much more than the list of founding institutions:
Which public blockchains will be supported?
Who will legally issue the stablecoin?
What assets will constitute the reserves?
Who will custody those reserves?
Who can redeem directly?
Will retail users have access?
How will transaction monitoring and sanctions controls work?
How will governance be divided between members?
And what will make businesses or blockchain users choose this stablecoin instead of existing alternatives?
Those answers will define the product.
Until then, the proposed 2027 launch should be treated as a plan rather than a certainty.
The Bigger Picture
Stablecoins were once easy for traditional finance to treat as a crypto-market instrument.
That distinction is becoming harder to maintain.
Crypto-native issuers have demonstrated that tokenized dollars can operate globally across blockchain networks.
Governments are creating regulatory frameworks around them.
Financial institutions are experimenting with tokenized deposits.
Asset managers are bringing securities on-chain.
Banks are exploring blockchain-based settlement.
And now 21 major financial institutions are attempting to create a shared stablecoin enterprise.
None of this means stablecoins will replace bank deposits.
It does not mean bank-backed tokens will displace USDT or USDC.
And it does not guarantee that this particular consortium will achieve meaningful adoption.
It means something more fundamental.
The debate inside traditional finance is shifting from whether money will exist on blockchain networks to what form that money should take — and who should be allowed to issue it.
That makes the proposed stablecoin important even before the first token exists.
The consortium is not simply launching another digital dollar.
It is testing whether some of the world's largest financial institutions can transform their existing relationships into a shared on-chain monetary network.
If they succeed, stablecoin competition may no longer be defined primarily by crypto companies competing against one another.
It could become a contest between entire financial networks.
Primary Sources & Data
- 21-Institution Consortium Announcement: Official September 2026 announcement detailing participating institutions, the planned operating company, 1:1 reserve backing, public-blockchain compatibility, expected 2027 U.S. dollar stablecoin launch and potential expansion to other G7 currencies.
- U.S. GENIUS Act: Federal legislation establishing the U.S. regulatory framework for payment stablecoins and permitted issuers.
- Qivalis: Official information on the European banking consortium developing a regulated euro-denominated stablecoin.
- Reuters: Reporting used for consortium context, existing stablecoin market scale and comparisons with other institutional stablecoin initiatives.
Sources & Methodology
This analysis prioritizes primary documentation from the institutions developing the stablecoin project, official regulatory material and direct statements from comparable institutional initiatives.
Secondary reporting is used where it provides market data or additional context not contained in the primary announcements.
The Crypto Public distinguishes between announced plans and operating products. The consortium's stablecoin has not yet launched, and details including supported blockchains, final reserve composition, governance, redemption mechanics and user access remain subject to future announcements and regulatory requirements.
Market comparisons are intended to explain competitive structure and network effects rather than predict which stablecoin or issuer will succeed.
Responses (0 )